

Table of Contents
US insurers are being squeezed from several sides: customers who expect banking-grade digital service, climate-driven losses that are harder to price, legacy platforms that slow every change, and AI tools that arrived faster than most governance programs. The winners will not be the carriers that buy the most technology. They will be the ones that redesign how underwriting, claims, and service actually work.
This guide covers 12 insurance transformation trends for 2026, what each means in practice, and how to sequence them without disrupting the systems you already run.
What Is Digital Transformation in Insurance?
Digital transformation in insurance is the redesign of underwriting, claims, policy administration, and customer service around modern technology such as AI, cloud, data platforms, and APIs. The goal is faster decisions, lower operating costs, and better policyholder experiences, not simply new software.
It touches every part of the value chain: how risks are assessed, how claims are settled, how policies are administered, how agents and brokers work, and how new products reach market. For many insurance companies, that starts with custom insurance software that replaces or extends aging core platforms. It is also broader than InsurTech. InsurTech describes technology companies and tools built for insurance; transformation is the organizational change that puts them to work.
| Layer | What it includes |
|---|---|
| Technology | AI, cloud, APIs, analytics, IoT |
| Operations | Claims, underwriting, policy administration, service |
| Business outcomes | Efficiency, accuracy, lower costs |
| Customer outcomes | Speed, personalization, trust |
Treat this as a chain. Technology matters only when it changes operations, and operations matter only when they move a business or customer outcome.
12 Insurance Transformation Trends Shaping the Industry in 2026
1. Enterprise AI and Agentic AI
Three things are often blurred together. Traditional AI automation follows fixed rules or predictions for a narrow task, such as scoring a claim. Generative AI reads and writes language, so it can summarize a policy or draft a response. Agentic AI chains steps together: it gathers information, uses tools, checks its own work, and hands off to a person when needed.
Practical example. An AI agent receives a commercial submission, extracts data from the attachments, flags missing information, drafts a risk summary, and routes it to an underwriter for the final call.
Business benefit. Less time spent on document handling and more on judgment.
Implementation note. Most carriers are further along on this path than they think. In KPMG’s 2026 global survey of insurance leaders (20 countries, conducted in May 2026), 71% said they use AI mainly for content generation and routine task automation, and only 29% run end-to-end processes through AI agents or automation. Just 11% reported strong data foundations and governance for scaling AI, and just 11% had very clear ROI metrics. The gap between pilots and production is a data, integration, and governance problem more than a model problem. Our AI development services focus on closing that gap.
2. Intelligent Claims Processing and Automation
Claims is where policyholders judge an insurer, and where manual effort is highest. Modern claims automation covers First Notice of Loss (FNOL) intake, document extraction and validation, computer vision for property and vehicle damage, routing, and fraud indicators.
Practical example. A policyholder uploads photos of vehicle damage. Computer vision estimates the repair scope, AI extracts the claim details, and the system routes the claim by complexity and risk.
Straight-through vs. AI-assisted. Straight-through processing settles simple, low-risk claims with no human touch. AI-assisted handling prepares the file and recommends actions, but an adjuster decides. Most insurers need both, with clear rules on which claims qualify for each.
Business benefit. Faster settlement, lower handling costs, and adjusters freed for complex cases.
Implementation note. Fraud flags should open an investigation, not deny a claim automatically.
3. AI-Powered Underwriting and Predictive Risk Assessment
Machine learning can score risk, read submission documents, and pull in external data in near real time. Underwriters spend less time re-keying information and more time evaluating it.
Practical example. A commercial property insurer combines building characteristics, location risk data, historical claims, and weather exposure into a single view that supports the underwriter’s pricing decision.
Business benefit. Faster quotes, more consistent selection, and better risk differentiation.
Implementation note. AI should support accountable underwriters, not silently replace them. Explainable models, documented rationale, and clear override paths protect both the customer and the carrier.
4. Cloud-Native Platforms and Legacy Modernization
Many policy administration and claims systems were built decades ago and still hold critical logic. Replacing them in one move is rarely realistic. Modernization typically combines cloud-native services, microservices, hybrid or multi-cloud hosting, and API layers that let new applications work with the old core.
Practical example. An insurer moves claims analytics to the cloud while keeping its existing policy administration system, linking the two through APIs.
Business benefit. Scalability, lower maintenance burden, and a path to retire legacy components gradually.
Implementation note. Low-code and no-code tools can help here too. Mature enterprise platforms now let business teams build internal workflows under IT governance, which relieves backlogs. See our overview of low-code platforms for developers. For planning and execution, explore our digital transformation services and AWS cloud migration services.
5. Data Engineering, Real-Time Analytics, and Unified Customer Data
Policy, claims, billing, and CRM data often live in separate systems with different definitions of the same customer. Every AI use case in this list depends on fixing that. Insurers are building governed data platforms, using lakes and warehouses, streaming pipelines, and clear lineage and quality controls.
Practical example. An insurer consolidates customer, policy, payment, and claims data into one governed platform, giving underwriters and service teams the same trusted view.
Business benefit. More accurate risk assessment, better customer insight, and AI that can be trusted.
Implementation note. Start with the data your first use case needs rather than boiling the ocean. Our data engineering services are built around that approach.
6. API-First Architecture and Insurance Ecosystems
An API-first approach exposes quoting, policy, billing, and claims functions as reusable services. Insurers can then add digital front ends, partner integrations, and broker tools without rebuilding the core. A related idea, headless architecture, separates the customer-facing front end from back-end systems, which is especially useful where legacy platforms limit the user experience.
Practical example. An auto dealership connects to an insurer’s quoting API so buyers can see coverage options during the vehicle purchase.
Business benefit. Faster product launches and easier partner onboarding.
Implementation note. Invest in API governance: versioning, security, rate limits, and monitoring.
7. Personalized Products and Usage-Based Insurance
Usage-based insurance (UBI) prices coverage on observed behavior such as mileage, braking, and time of day rather than broad demographic groups. Pay-as-you-drive and pay-how-you-drive are the best-known forms, and similar models are emerging with wearables and connected-home data. Tailored digital products depend on the same foundations: good data and fast product engineering. Even the life settlement market, once reliant on opaque, manual valuation, is now using data to offer more transparency, faster valuations, and a better policyholder experience.
Practical example. A telematics-enabled auto insurer evaluates mileage and braking patterns to offer risk-based pricing and driver feedback.
Business benefit. Fairer pricing for low-risk customers and stronger product differentiation.
Implementation note. Privacy, informed consent, and fairness are central. Be transparent about what is collected and how it affects price, and test for unintended discrimination.
8. IoT, Telematics, and Connected Risk Monitoring
Connected vehicles, smart-home sensors, industrial equipment, and wearables turn insurance from after-the-fact payment into ongoing risk monitoring. Data can flag problems early, and that benefits both parties.
Practical example. Water-leak sensors in a commercial property alert the owner to abnormal flow before a small leak becomes a major loss.
Business benefit. Lower loss frequency and severity, and a reason for customers to engage between renewals.
Implementation note. Device data is high-volume and messy. Plan for ingestion, device security, and clear data-sharing agreements. Our IoT development team builds this kind of connected-device infrastructure.
9. Digital Customer Experience and Omnichannel Self-Service
Policyholders expect to quote, buy, change, and claim on the channel they prefer, then switch to a person without starting over. That means customer portals, mobile apps, digital onboarding, automated renewals, and AI assistants backed by the same customer record across channels. Agents and brokers need equally good tools. AI voice assistants such as Sonant now answer routine policy and claims calls and escalate complex ones to human staff.
Practical example. A policyholder starts a claim in the mobile app, uploads documents, receives status updates, and later speaks with a representative who already has the full history.
Business benefit. Higher satisfaction and retention, with lower service cost.
Implementation note. Self-service fails when it dead-ends. Always design the handoff to a human. See why customer experience engineering drives growth, or explore our customer experience engineering services.
10. Embedded Insurance and Digital Distribution
Embedded insurance puts coverage inside another purchase journey: at checkout, at vehicle sale, or within a banking or travel app. Conventional online distribution asks the customer to come to the insurer. Embedded distribution brings the policy to the customer at the moment of need, usually through APIs and partner integrations.
Practical example. A travel platform offers trip insurance at checkout through an integrated carrier.
Business benefit. New customer acquisition and revenue channels with lower friction.
Implementation note. Success depends on clean partner APIs, quick underwriting decisions, and a clear plan for servicing claims after the sale.
11. Cybersecurity, AI Governance, and Regulatory Compliance
More data, more APIs, and more AI widen the attack surface and the compliance burden. Core practices include encryption, access controls, audit trails, third-party vendor oversight, and model governance covering explainability and bias monitoring.
In the US, insurance regulation is state-based, and there is no single federal insurance AI law. The NAIC Model Bulletin on the Use of Artificial Intelligence Systems by Insurers, adopted in December 2023, is guidance that sets expectations for governance, testing, documentation, and vendor oversight. It becomes enforceable through individual state adoption, and by 2026 roughly half of states have adopted it or substantially similar guidance, with some states adding their own rules. Multi-state carriers should check each jurisdiction and consult counsel.
Accountability. Name an owner for each AI system, keep a model inventory, document testing, and define when humans must review decisions. KPMG found only 15% of insurers had AI governance fully integrated into strategic planning.
Business benefit. Trust with customers and regulators, and fewer surprises in market conduct exams.
12. Predictive Analytics, Climate Risk, and Proactive Insurance
Catastrophe exposure and climate volatility are pushing insurers toward geospatial analytics, predictive loss modeling, and continuous monitoring. The long-term shift is from reimbursing losses to helping prevent them.
Practical example. A property insurer combines weather forecasts, satellite imagery, geographic data, and claims history to identify properties exposed to severe weather and to prioritize mitigation outreach and underwriting review.
Business benefit. Better pricing and capacity decisions, fewer avoidable losses, and a stronger customer relationship.
Implementation note. Model outputs need expert review and clear communication, especially where they affect availability or pricing.
How These Insurance Transformation Trends Compare
| Trend | Primary application | Main business benefit |
|---|---|---|
| Agentic AI | End-to-end workflows | Productivity |
| Claims automation | Claims assessment | Faster processing |
| AI underwriting | Risk evaluation | Decision support |
| Cloud modernization | Core infrastructure | Scalability |
| Data engineering | Data integration | Better intelligence |
| API architecture | Ecosystem integration | Faster innovation |
| Usage-based insurance | Personalized pricing | Product differentiation |
| IoT and telematics | Risk monitoring | Loss prevention |
| Digital self-service | Customer operations | Better experience |
| Embedded insurance | Digital distribution | New revenue channels |
| Cybersecurity and AI governance | Risk and compliance | Trust and resilience |
| Predictive analytics | Climate and exposure risk | Proactive risk management |
What Are the Business Benefits of Insurance Digital Transformation?
The individual trends add up to six outcomes that executives can track.
Reduced Operational Costs
Less manual document handling, fewer rework loops, and optimized infrastructure lower the cost to serve.
Faster Claims and Underwriting
Automated intake, triage, and data gathering shorten turnaround, so customers and brokers get answers sooner.
Better Risk Assessment
Unified data and predictive models give underwriters more relevant information at the point of decision.
Improved Customer Retention
Transparent, convenient digital service and personalized offers give customers fewer reasons to shop around.
Faster Product Innovation
Modular platforms and APIs let teams launch and adjust products without multi-year replatforming.
Greater Business Resilience
Scalable infrastructure, strong security, and proactive risk management help carriers absorb shocks.
The benefits above are directional. Measure your own: baseline each KPI before you start, set a target, and track it over a defined period. Be cautious with vendor claims that lack a named source or sample.
How Can Insurance Companies Implement Digital Transformation?
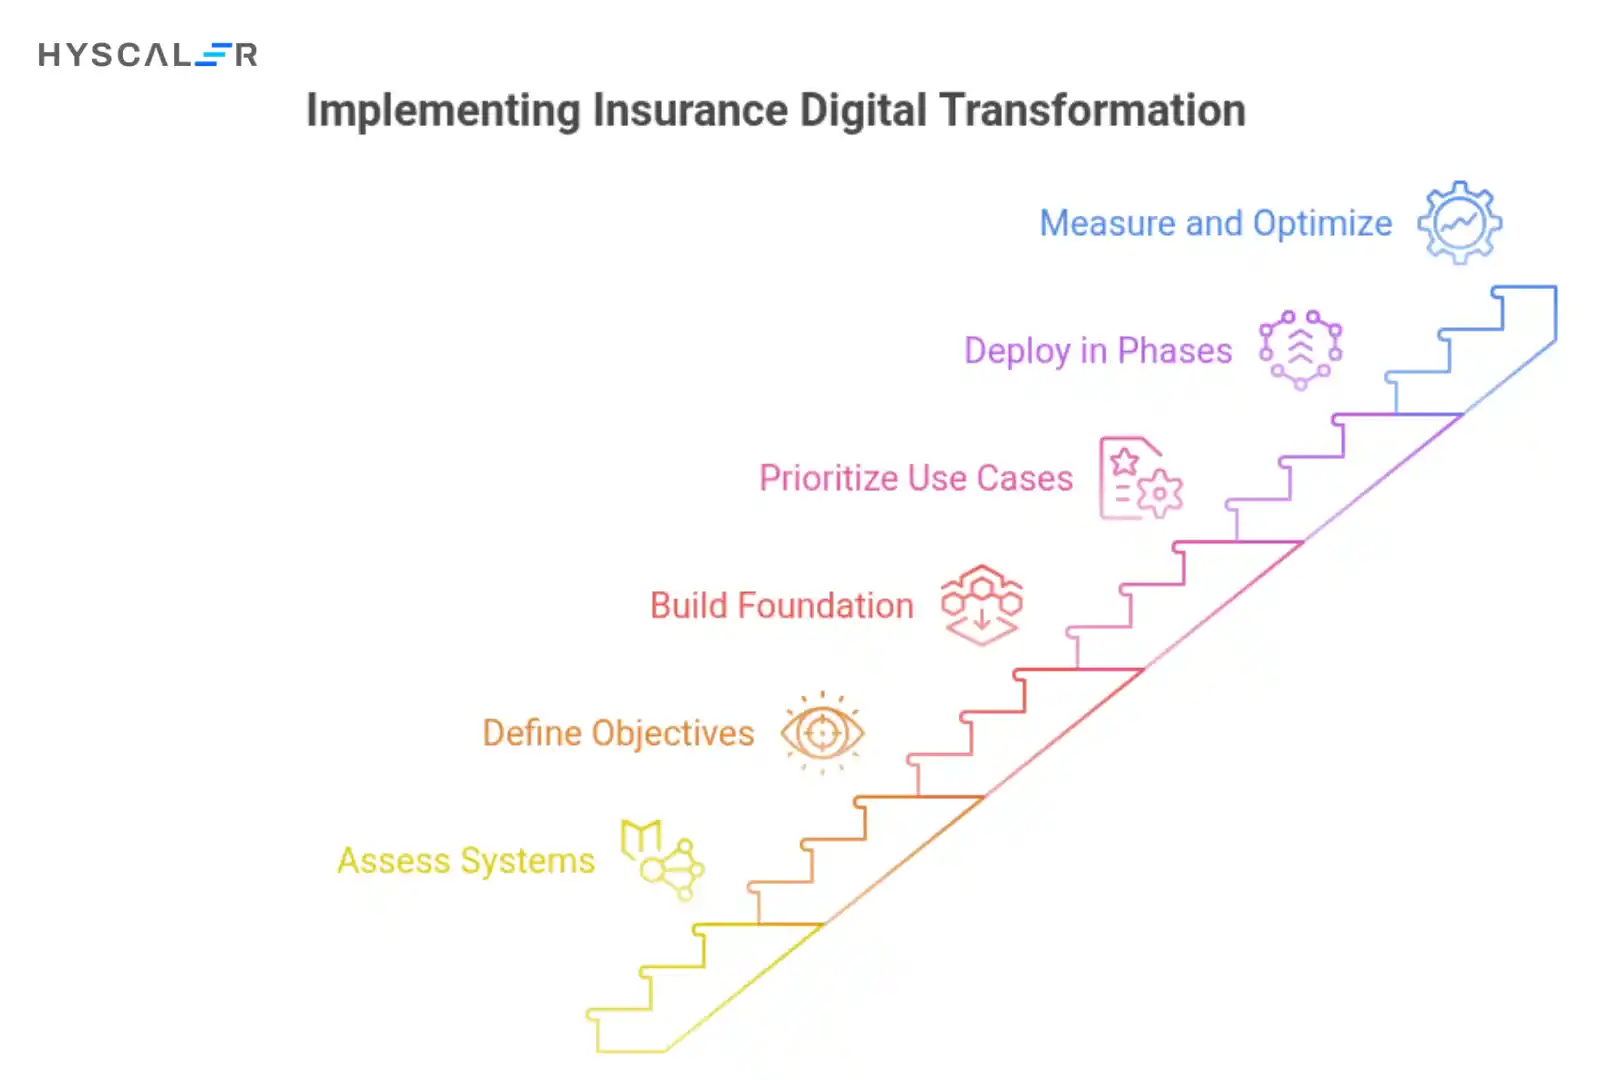
Most failed programs share a pattern: ambitious technology, vague objectives, and weak data. A staged approach reduces risk.
- Assess existing systems and processes. Map legacy constraints, manual workflows, data silos, and bottlenecks.
- Define business objectives and KPIs. Set targets for claims turnaround, underwriting efficiency, customer satisfaction, and operating cost.
- Build the data and cloud foundation. Establish integration architecture, data quality, security, and scalable infrastructure.
- Prioritize high-value use cases. Begin where value is clear and risk is manageable, such as claims document processing, underwriting assistance, or self-service.
- Integrate and deploy in phases. Connect new applications to existing systems and validate each workflow before scaling.
- Measure, govern, and optimize. Track outcomes, monitor AI performance, and improve continuously.
Example path. A mid-sized carrier starts with claims document automation, where volumes are high, and outputs are easy to verify. Once the data pipeline and review process are proven, it reuses them for an underwriting assistant and then for customer servicing.
Challenges of Insurance Digital Transformation and How to Address Them
| Challenge | Business impact | Recommended approach |
|---|---|---|
| Legacy infrastructure | Slow integration and high maintenance costs | Phased modernization |
| Fragmented data | Inconsistent decisions | Unified data architecture |
| AI reliability | Incorrect or biased decisions | Validation and human oversight |
| Cybersecurity | Exposure of sensitive information | Security by design |
| Regulatory complexity | Compliance and audit risk | Embedded governance |
| Skills shortages | Slow adoption | Workforce training and expert partnerships |
| Unclear ROI | Poor investment decisions | KPI-based implementation |
People are part of this list too. In the KPMG survey, only 8% of insurers rated their workforce as highly proficient with AI tools. Training and change management deserve real budget.
What Is the Future of Insurance Transformation?
Already happening: claims document automation, AI-assisted underwriting, cloud and API modernization, and usage-based pricing. These are in production at many carriers today.
Emerging: agentic AI coordinating multi-step workflows across departments, continuous risk monitoring and prevention services, deeper participation in partner ecosystems, and more modular, interoperable platforms. KPMG found that no surveyed insurer had fully redesigned underwriting or distribution around AI, so this is still early territory with room for advantage.
The direction is consistent: AI-assisted humans making better decisions, and insurers moving from paying for losses toward helping prevent them.
Conclusion: Turning Insurance Technology Into Business Value
Three messages stand out:
- Transformation requires business and technology change together.
- AI depends on reliable data, modern infrastructure, and governance.
- Prioritize use cases with measurable operational and customer outcomes.
HyScaler helps insurers modernize legacy systems, build AI solutions, and integrate enterprise applications without disrupting what already works. Talk to an engineer about where to start.
FAQ
How much does digital transformation cost for an insurance company?
There is no universal price. Cost depends on legacy complexity, integration needs, data migration, licensing, security requirements, and scope. A focused claims automation project costs far less than an enterprise-wide program, which is why phasing and clear KPIs matter.
Should insurers replace legacy systems or modernize them gradually?
Full replacement suits platforms that are truly end-of-life and where the business can absorb the risk. Phased modernization and API-based integration fit most carriers, since they deliver value sooner and avoid a single high-stakes cutover.
Can small and mid-sized insurers benefit from AI?
Yes. Targeted use cases such as document processing, claims triage, and customer service assistants can run on cloud services without an enterprise-scale program. Start small and prove value first.
How long does an insurance digital transformation project take?
It varies widely. A single workflow automation may take months, application modernization longer, and enterprise-wide transformation multiple years delivered in phases.
How can insurers ensure AI decisions are fair and explainable?
Use model validation, bias testing, audit trails, documented rationale, human review for consequential decisions, and an owner for each system, in line with NAIC and state expectations.
What technologies are used in modern claims management?
AI, OCR, computer vision, workflow automation, predictive analytics, and API integrations with policy, payment, and partner systems.